

Bank or NBFC: Why a Personal Loan from an NBFC Might Be Better For You
Every year, more Indians are choosing a personal loan from an NBFC over a traditional bank loan — and it isn’t just about speed. From flexible eligibility to faster disbursal, NBFCs like AFI Loans (Ayaan Finserve India Pvt. Ltd.) are changing how India borrows.
If you’ve ever been rejected by a bank for a “low” CIBIL score, an irregular income, or incomplete paperwork, this guide is for you. We’ll break down exactly how a personal loan from an NBFC compares to a bank loan — with real numbers, not just theory.
What Is an NBFC Personal Loan?
An NBFC (Non-Banking Financial Company) is an RBI-registered financial institution that lends money but cannot accept savings or current account deposits like a bank. Because NBFCs raise funds from banks, mutual funds, and bond markets rather than cheap public deposits, they price risk differently — which is exactly why NBFC personal loan approval criteria are more flexible than a bank’s.
Every RBI-registered NBFC — AFI Loans included — is bound by the same fair-practice and disclosure norms as banks, just under a different regulatory chapter of the RBI Act. So “NBFC” doesn’t mean unregulated; it means a different lending model built for speed and accessibility.
Bank vs NBFC Personal Loan: The Real Numbers (2026)
| Parameter | Bank Personal Loan | NBFC Personal Loan (like AFI Loans) |
|---|---|---|
| Interest Rate (p.a.) | ~10% – 16% | ~11% – 26% |
| Minimum CIBIL Score | 700 – 750+ preferred | 600 – 650+ accepted |
| Approval Time | 5 – 15 days | 24 – 72 hours (often same-day) |
| Documentation | Extensive, paper-heavy | Minimal, mostly digital |
| Income Proof Flexibility | Strict — salaried, formal income only | Flexible — self-employed, gig, informal income considered |
| Processing Fee | 0.25% – 1.5% | 1% – 3% |
| Collateral | None (unsecured) | None (unsecured) |
| Best Suited For | High CIBIL, stable salaried employees | First-time borrowers, self employed, urgent need |
Rates are indicative starting rates for 2026 and vary by applicant profile, lender policy, and RBI’s prevailing repo rate.
Why Approval Speed Matters More Than the Headline Rate
A lower advertised rate is only a good deal if you actually qualify for it. Most borrowers don’t get a bank’s headline rate — they get 2–5% above it, if they get approved at all. This is where the real comparison starts to favour NBFCs for a large chunk of Indian borrowers.
Loan Approval Speed: Bank vs NBFC
| Stage | Bank | NBFC |
|---|---|---|
| Application to initial approval | 3–7 days | Same day – 24 hrs |
| Document verification | 2–5 days | Digital, near-instant |
| Disbursal after approval | 2–3 days | Within 24–48 hrs |
| Total time to money in account | 7–15 days | 1–3 days |
Who Actually Qualifies? A CIBIL Score Breakdown
| CIBIL Score Band | Bank Access | NBFC Access | Typical Rate Band |
|---|---|---|---|
| 750+ | Full access, best rates | Full access | 9.99% – 12% |
| 650 – 749 | Limited, higher rate | Good access | 12% – 18% |
| 600 – 649 | Rarely approved | Access with most NBFCs | 18% – 24% |
| Below 600 | Almost never approved | A few NBFCs only | 24%+ or rejected |
The takeaway: if your score sits between 600–749 — which covers a very large share of first-time and young borrowers in India — an NBFC personal loan is often your realistic, fastest path to funds, while a bank may reject the application outright.
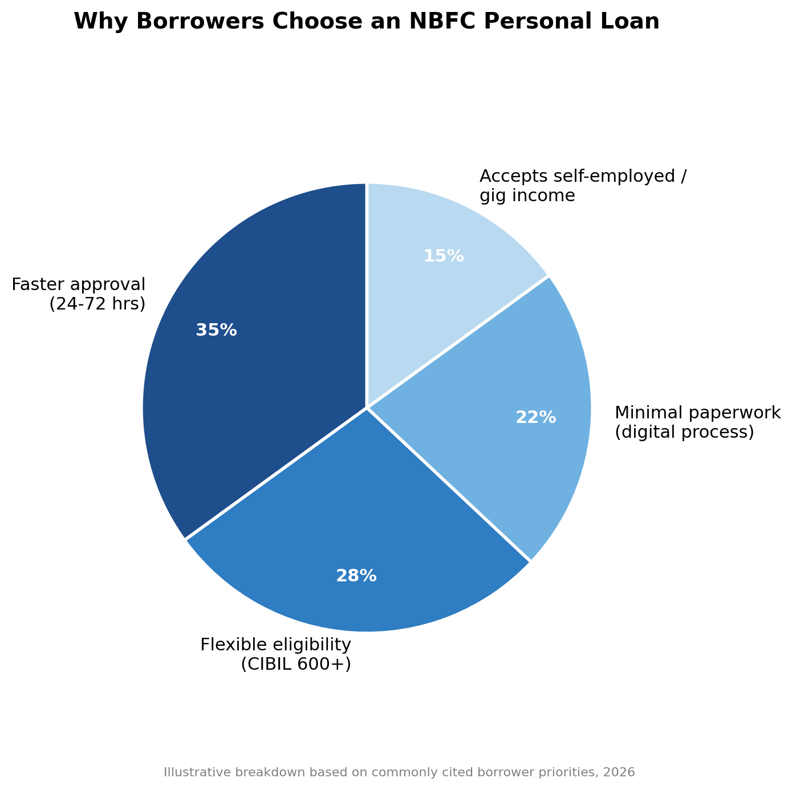
4 Reasons Borrowers Are Choosing NBFCs in 2026
- Digital-first process — Aadhaar-based e-KYC, digital income assessment, and paperless disbursal mean you rarely need to visit a branch.
- Alternative credit assessment — NBFCs increasingly use AI-based underwriting and alternative data (UPI transaction history, utility payments) instead of relying purely on CIBIL.
- Flexible income proof — Self-employed professionals, freelancers, and gig workers who struggle with bank paperwork find NBFCs far more accommodating.
- Speed in emergencies — Medical bills, urgent home repairs, or a sudden expense don’t wait 15 days. NBFC disbursal timelines are built for exactly this.
When a Bank Might Still Be the Better Choice
To be fair, banks aren’t obsolete for personal loans:
- If your CIBIL score is 750+ and income is well-documented, a bank’s lower headline rate will usually cost you less over the loan tenure.
- If you already have a strong banking relationship (salary account, existing loans repaid on time), banks often extend preferential rates.
- For very large loan amounts and long tenures, the rate difference compounds — worth the extra paperwork and wait.
How to Choose: A Quick Decision Framework
- Need money fast, imperfect paperwork, average CIBIL? → NBFC personal loan
- High CIBIL, stable salary, can wait 1–2 weeks? → Bank personal loan
- Self-employed or informal income? → NBFC personal loan
- Large amount, long tenure, want the lowest possible rate? → Compare bank offers first
Applying for a Personal Loan with AFI Loans (Dhanvriddhi)
AFI Loans, the personal loan product of Ayaan Finserve India Pvt. Ltd. (RBI-registered NBFC), is built around the same principle: get money to people who need it, without the wait a bank forces on them. With Dhanvriddhi’s digital application process, most eligible applicants get a decision within hours, not weeks — with EMI repayment rewards through Loyal-Pay redeemable on platforms like Amazon Prime, MakeMyTrip, and Ajio for on-time payments.
You Might Also Like
- Looking for a Private Financer in Delhi NCR for a Personal Loan?
- How to Apply for an Online Personal Loan, Step by Step
- Instant Loan Online: The Best Digital Lending Platforms in India
Frequently Asked Questions
1. Is a personal loan from an NBFC safe to take?
Yes. An RBI-registered NBFC personal loan, like the one offered by AFI Loans, is regulated under the RBI Act and follows the same Fair Practices Code as banks regarding disclosures, interest rates, and grievance redressal.
2. What documents are required for an NBFC personal loan?
Most lenders ask for basic KYC (PAN, Aadhaar), income proof (salary slips or bank statements for the self-employed), and a photograph. Because the personal loan NBFC process is largely digital, most of this can be uploaded online instead of couriered or submitted in person.
3. Why are NBFC personal loan interest rates higher than banks?
NBFCs borrow their lending capital from banks and markets (rather than low-cost public deposits), which raises their cost of funds — this is passed on as a slightly higher interest rate on an NBFC personal loan in exchange for faster approval and flexible eligibility.
4. Can I get an NBFC personal loan with a CIBIL score below 650?
Many NBFCs, including those with alternative underwriting models, do consider applicants in the 600–650 range for a personal loan NBFC application, though at a higher interest rate than someone with a 750+ score.
5. How fast can I get money from an NBFC personal loan?
Most digital-first lenders offering a personal loan NBFC product disburse within 24–72 hours of approval, compared to 7–15 days typically required by banks.
Sources
- RBI — Regulatory framework for NBFCs: rbi.org.in
- CIBIL — Understanding your credit score: cibil.com
- Paisabazaar — Personal Loan Interest Rates 2026: paisabazaar.com
- OnePaisa — Personal Loan Interest Rate Comparison India 2026: onepaisa.in
- Saarathi FinBiz — Bank vs NBFC Personal Loans: saarathi.ai
Share this post: